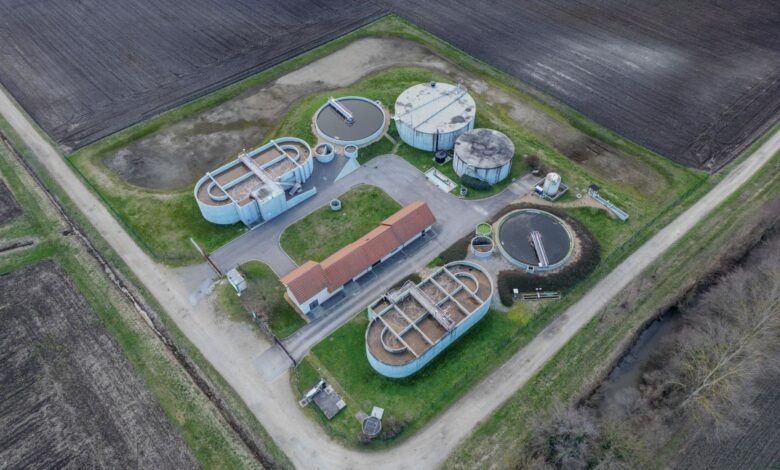
A quiet consolidation is reshaping the American water treatment industry. Across the country, family-owned and regionally operated water and wastewater treatment firms are signing over their operations to Veolia Water Technologies and Solutions – often with minimal public fanfare and little notice beyond the local business pages.
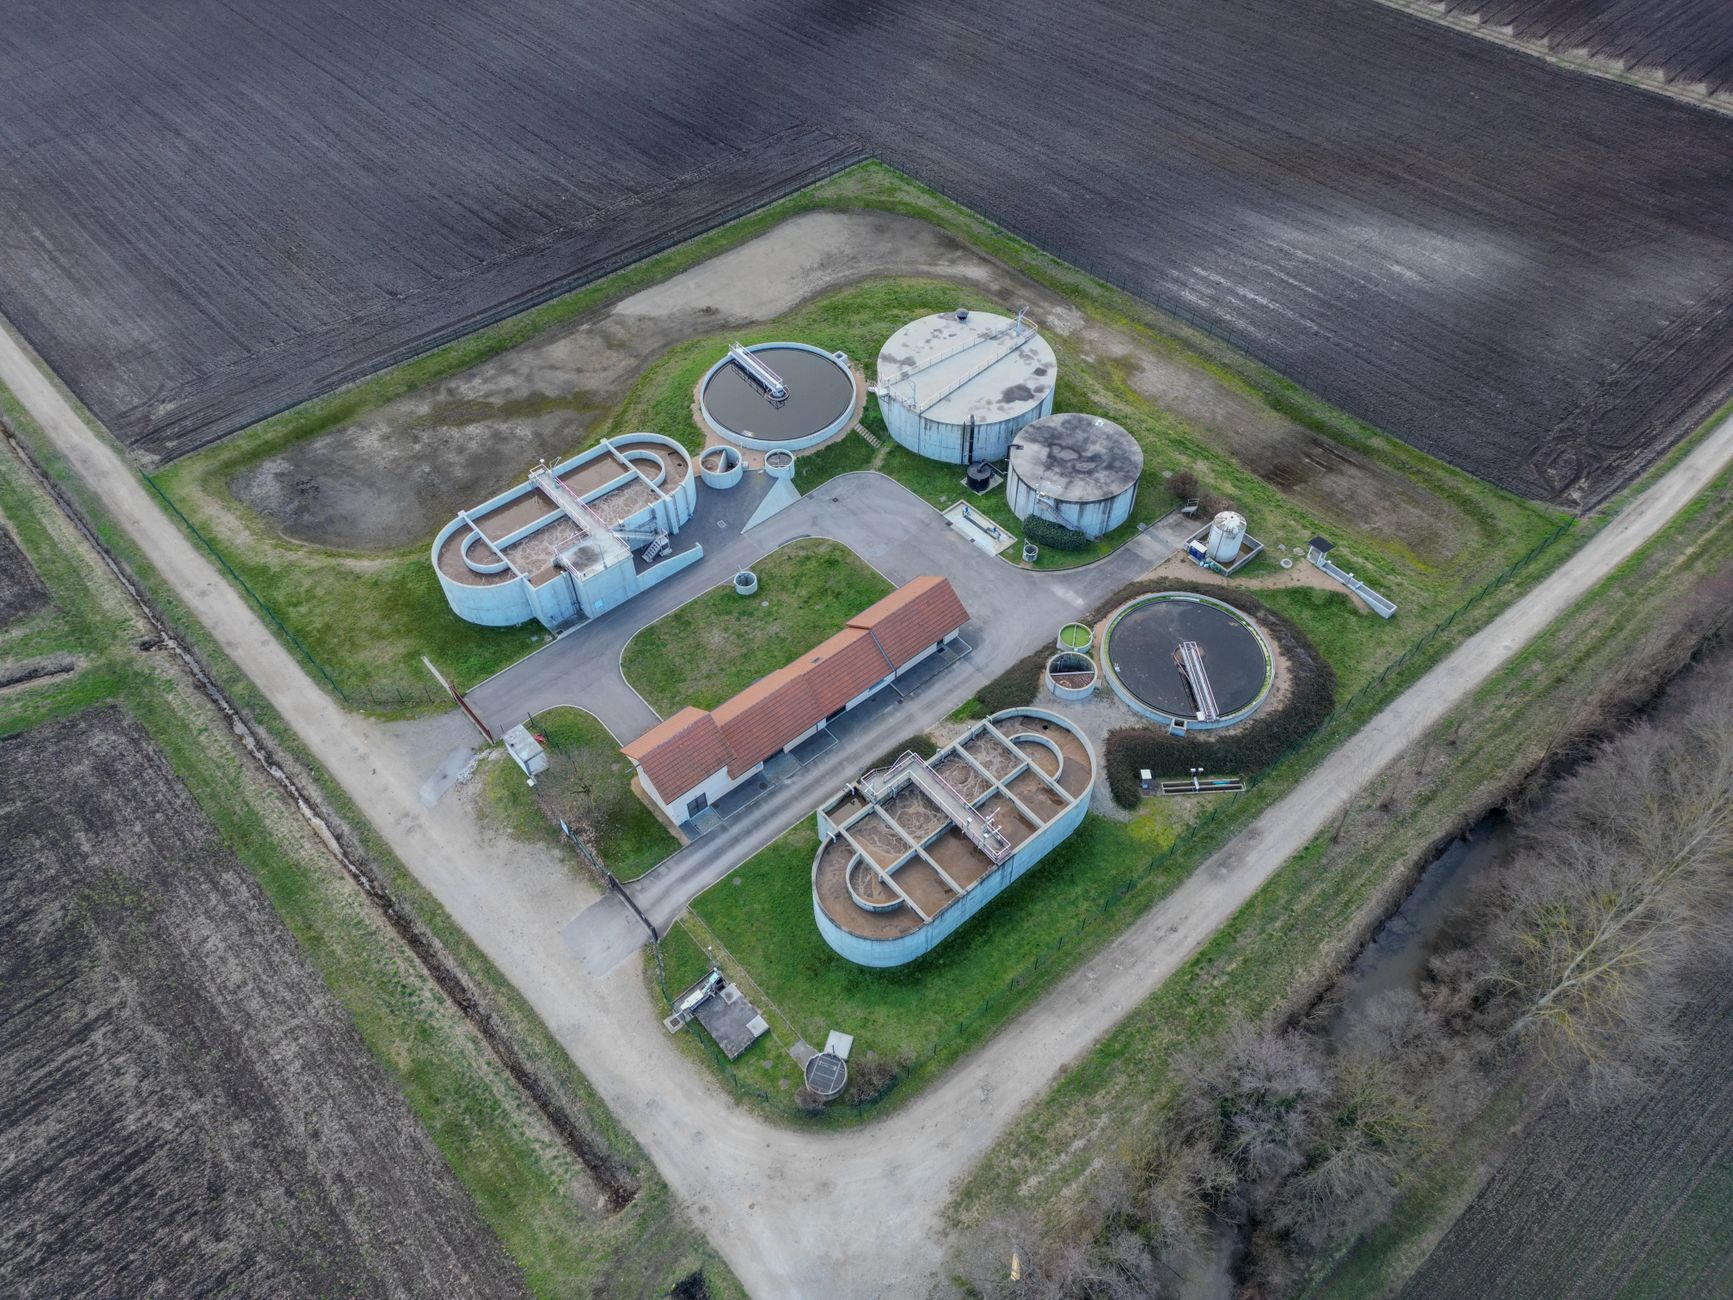
The Pattern Taking Shape Across the Country
Veolia, the French multinational utility giant, has been building its North American water treatment footprint for years through a methodical acquisition strategy. Rather than pursuing headline-grabbing megadeals, the company has focused on absorbing smaller regional operators – municipal contract holders, industrial water treatment specialists, and wastewater management firms that service mid-market clients. The result is a slow-moving but steady accumulation of local expertise, client contracts, and operational infrastructure.
The sellers are often firms that have operated under the same ownership for decades. Water treatment is a deeply relationship-driven business. Local operators build long-term contracts with municipalities, food processors, pharmaceutical manufacturers, and industrial facilities that depend on consistent, regulation-compliant water management. When a founder approaches retirement age with no clear succession plan, selling to a larger operator with the technical depth and capital to maintain compliance becomes the most logical exit. Veolia, in many of these situations, is positioned as a known quantity – a company the regional firm has likely competed against or partnered with at some point.
What accelerates this trend is the growing complexity of water regulation. The Environmental Protection Agency has been tightening standards around per- and polyfluoroalkyl substances, commonly known as PFAS, and updated limits on lead, nitrates, and emerging contaminants have raised the technical bar for compliance across the board. Smaller firms that could manage these standards with a lean team five years ago are now facing the need to invest in new testing equipment, updated treatment processes, and specialized staff. That capital burden shifts the math on independent ownership considerably.
This pattern closely mirrors what has played out in other fragmented service industries where compliance costs and aging ownership have created natural acquisition windows. Regional insurance adjusting firms selling to Sedgwick followed a near-identical trajectory – operators with deep local networks, proprietary client relationships, and no institutional succession plan, absorbed by a national platform equipped to absorb the overhead that independent shops increasingly cannot.
Why Veolia, and Why Now
Veolia completed its acquisition of Suez in 2022, creating the largest water and waste management company in the world by revenue. That deal drew significant regulatory scrutiny and required the divestiture of several assets to satisfy antitrust conditions. What followed was a period of internal integration – but also an intensified push into the North American market, where Veolia has historically held less dominant ground than in Europe and emerging markets. Acquiring regional operators is, in effect, how Veolia builds market share in the United States without triggering the kind of antitrust review that a direct play for a major national competitor would invite.
For the regional sellers, the calculus involves more than just retirement planning. Water treatment contracts with municipalities and industrial clients are long-duration agreements, often spanning five to ten years. When a small firm sells, those contracts transfer – and Veolia’s ability to service them at scale, with broader engineering resources and geographic redundancy, often makes Veolia an attractive buyer from the client’s perspective as well. Municipal water authorities and large industrial purchasers generally prefer counterparties with the institutional depth to handle emergency response, regulatory filings, and capital-intensive upgrades without disruption.
The pricing dynamics favor sellers right now. Water infrastructure has become an asset class that institutional investors take seriously, partly driven by federal funding flowing through the Infrastructure Investment and Jobs Act, which allocated billions for water system upgrades across states. That federal spending has raised the profile and perceived value of water treatment operations. Regional operators who might have received modest multiples on earnings a decade ago are now fielding more competitive offers, because Veolia and its peers understand that any firm with an established contract base in a federally prioritized infrastructure segment carries strategic value beyond its immediate revenue.
There is also a workforce dimension that rarely surfaces in transaction announcements. Skilled water treatment operators – licensed engineers, plant operators with state certifications, and industrial chemistry specialists – are genuinely difficult to recruit. When Veolia acquires a regional firm, it is not only buying contracts and equipment. It is buying a trained workforce and, critically, the institutional knowledge those employees carry about local water chemistry, seasonal treatment challenges, and the specific compliance history of the sites they manage. Replicating that knowledge through organic hiring would take years.
Not every deal is smooth. Some municipal clients have raised concerns when a longtime local operator is absorbed by a multinational. The worry is straightforward: will service quality hold, will local decision-making authority remain, and will pricing stay competitive once the competitive pressure of a smaller local alternative disappears? These concerns have surfaced in public comments at water authority board meetings in several states, though they have rarely been enough to block a transaction or void a contract transfer once the deal is finalized.
What Comes Next for the Industry
The segment of the water treatment market that remains genuinely independent is shrinking. Firms with fewer than 50 employees, single-state footprints, and founders in their sixties represent the most likely next wave of sellers. Private equity has also entered the space, with several roll-up vehicles acquiring regional operators before positioning the combined entity for an eventual sale to a strategic buyer like Veolia or its competitors. That intermediate layer of PE consolidation means Veolia sometimes acquires what was recently an independent firm only after private equity has already extracted one round of value from it – a compressed version of the same consolidation cycle playing out in healthcare, insurance, and professional services.
The municipalities and industrial clients sitting at the end of these ownership chains have limited tools to push back. Most water treatment contracts include change-of-control provisions, but exercising them is expensive and disruptive – finding a replacement operator, running a new procurement process, and managing a transition without interrupting treatment operations is a significant undertaking. In practice, most clients accept the ownership change, negotiate whatever service commitment language they can extract, and adapt. Whether that adaptation serves public water quality over a ten or twenty year horizon is a question the industry has not yet had to answer at scale.