The Quiet Exit of America’s Independent Guard Companies
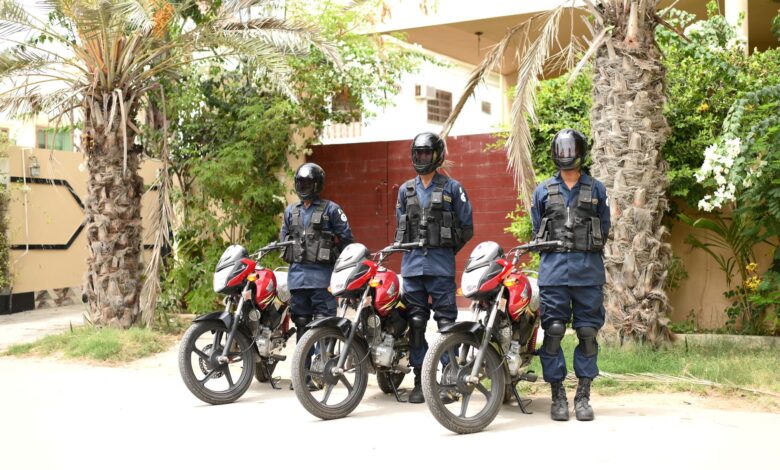
For decades, regional security guard firms built their businesses on local relationships – contracts with hospitals, shopping centers, office parks, and school districts that valued a familiar name and a consistent crew. Now, a growing number of those firms are selling, and the buyer showing up most often is Allied Universal, the Santa Ana, California-based security giant that has spent years assembling a national footprint through aggressive acquisition. The deals rarely make headlines, but the pattern is clear to anyone watching the private security labor market.
Allied Universal already employs more than 800,000 people across North America, making it the largest security services company on the continent by workforce. That scale didn’t happen through organic growth alone. The company has completed dozens of acquisitions in recent years, absorbing regional players from the Southeast, the Midwest, and the Mountain West, often with little public announcement beyond a brief press release about “expanding service capabilities.” The sellers, meanwhile, tend to cash out quietly and move on.
Why Owners Are Choosing to Sell Now
The decision to sell usually comes down to margin pressure and operational fatigue. Running a guard company sounds straightforward, but the economics are brutal. Firms bid contracts on thin margins, compete against each other on price, and then absorb the full cost of hiring, training, licensing, and scheduling workers – often at high turnover rates. When a contract is lost to a lower bid, there’s no inventory to liquidate and no recurring revenue to fall back on. The business bleeds immediately. Owners who built their companies in a lower-cost era now face minimum wage increases, insurance premium hikes, and clients who expect more technology – body cameras, incident reporting software, visitor management systems – without paying more for it.
The generational factor matters too. A significant share of independent security firm owners are in their late 50s or 60s, and the succession math rarely works in their favor. Training a family member or internal manager to run the business takes years, and private equity buyers – other than platforms like Allied Universal – have limited appetite for labor-heavy service firms with no proprietary technology. Allied Universal, by contrast, offers a clean exit. They know how to absorb guard companies operationally, they retain the existing contracts, and they typically keep local managers in place for continuity. For a tired owner with no clear heir and mounting back-office costs, that offer is hard to refuse.
Allied Universal’s Acquisition Logic
Allied Universal isn’t buying regional firms out of sentiment. Each acquisition brings a contract portfolio – often a mix of long-standing municipal, commercial, and healthcare accounts – that would take years to win through direct sales competition. Buying the company that already holds those contracts is faster and cheaper than displacing an incumbent vendor through a competitive bid process. The math works because Allied can immediately strip out the redundant corporate overhead of the acquired firm and run those contracts on its existing national infrastructure.
There’s a geographic logic at play as well. Allied Universal has national enterprise clients – large REITs, hospital systems, and retail chains – who want a single vendor managing security across dozens of locations in multiple states. To serve those clients well, Allied needs dense local presence in mid-size markets, not just major metros. Acquiring a regional firm in, say, a mid-size Southern city gives Allied the local workforce relationships, the state licensing infrastructure, and the existing municipal contracts that make it competitive for larger regional bids.
The company has also benefited from the consolidation trend in adjacent labor staffing markets, where similar rollup dynamics have played out. The playbook is familiar: buy the local player, retain the workforce and client relationships, standardize the back office, and use scale to underbid competitors on the next contract renewal cycle. It takes a few years, but the margin improvement from eliminating duplicated management layers is substantial.
What makes security firm acquisition particularly attractive is the contract structure. Commercial and institutional security contracts typically run one to three years with auto-renewal clauses, which means an acquired firm’s revenue base is relatively predictable for at least the first renewal cycle. Allied Universal’s deal teams can model the revenue retention probability with reasonable confidence before closing, which reduces the acquisition risk compared to businesses where revenue is more discretionary or one-time.
What Happens to the Workforce
For the guards themselves – the people actually doing the work – a sale to Allied Universal produces mixed outcomes. Pay rates and schedules often remain unchanged in the short term, because disrupting a workforce mid-contract is operationally risky. Allied Universal has its own wage structures by market, however, and over time, local pay practices tend to migrate toward the company’s standardized tiers. Some guards end up better off; others, particularly those who had informal arrangements with a longtime local owner – extra hours, flexible scheduling, cash advances during hard weeks – find the corporate structure less accommodating.
Union representation is another complicating factor. Several major U.S. cities have significant shares of security officers represented by SEIU 32BJ or other affiliates of the Service Employees International Union. When Allied Universal acquires a non-union firm operating in a unionized market, labor relations can become complicated quickly. The successor employer obligations under the National Labor Relations Act create legal obligations around recognition and collective bargaining that Allied Universal’s legal team navigates regularly, but the friction is real.
The Competitive Landscape Getting Narrower
Allied Universal isn’t the only consolidator. Securitas, the Swedish-headquartered multinational, has also been acquiring U.S. regional firms, as has Whelan Security and a handful of private equity-backed platforms targeting the lower-middle market. But Allied Universal’s scale gives it a structural advantage in acquisitions: it can pay a slightly higher multiple than a smaller competitor because the synergies it can capture on the back end are larger. That bidding advantage, compounded over years of deal-making, has produced a widening gap between Allied Universal and the next tier of competitors.
The regional firms that haven’t sold yet face a narrowing strategic path. Competing on price against Allied Universal’s scale is difficult without a comparable cost structure. Competing on service quality and local relationships is possible, but requires consistent investment in training and technology that eats into already-thin margins. Some regional firms have found a sustainable niche in specialized verticals – executive protection, event security, or cybersecurity-integrated physical security – where national firms are less competitive. But for the generalist guard company running mall and office park contracts in a mid-size metro, the pressure to sell is building with each contract renewal cycle.
The broader implication is that the security services industry, long defined by thousands of local and regional players, is quietly concentrating into a smaller number of very large firms. That concentration changes how contracts get negotiated, how labor disputes get resolved, and how new entrants can compete. A hospital or school district that once had five or six local bidders for its guard contract may soon find itself choosing between two or three national firms with similar pricing structures.
For the last generation of independent guard company owners still holding out, the calculation grows harder each year. The client pool isn’t shrinking, but the competitive conditions that allowed regional firms to thrive – fragmented markets, local loyalty, and a manageable operational scale – are eroding. The owners who sell in the next two years will likely get better multiples than those who wait until their client roster starts defecting to a larger competitor mid-contract, at which point the negotiating leverage shifts entirely to the buyer.
Allied Universal’s deal pipeline shows no signs of slowing. The company has publicly stated its intent to continue growing through acquisition, and regional security firm owners across the country are receiving unsolicited outreach from its corporate development team – some of them for the second or third time.