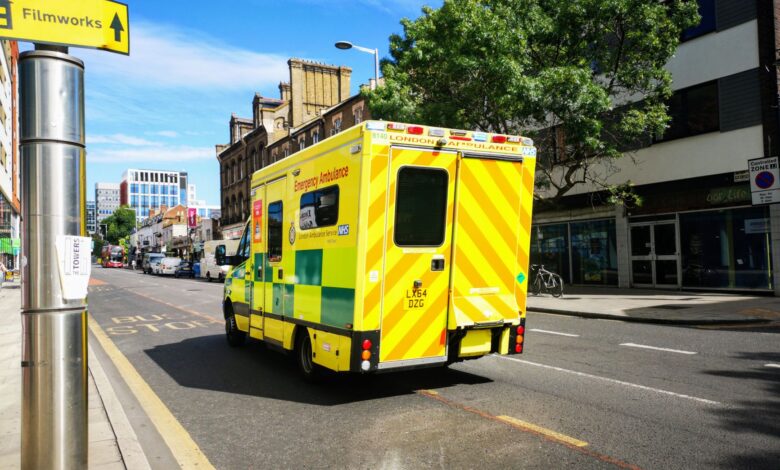
Across the country, small and mid-sized ambulance billing companies are quietly signing acquisition agreements with Air Methods Corporation – and most of their clients have no idea it’s happening until after the deal closes.
The Consolidation Nobody Saw Coming
Air Methods, best known as one of the largest air medical transport operators in the United States, has been expanding aggressively into the ground-level billing infrastructure that supports emergency medical services. The strategy is less about adding helicopters and more about controlling the revenue cycle that surrounds all emergency transport – air and ground alike. Regional billing groups that once operated as independent back-office operations for local EMS agencies are now finding themselves fielding acquisition offers, and the terms are frequently difficult to turn down.
The appeal for sellers is straightforward. Ambulance billing is a notoriously complex business – navigating Medicare reimbursement rules, state Medicaid contracts, and private insurer negotiations requires specialized staff, compliance infrastructure, and constant regulatory monitoring. Small billing shops that built their books of business over decades are now facing mounting software costs, tighter CMS audits, and a shrinking pool of trained coders willing to work in a niche vertical. Selling to a well-capitalized operator removes all of that overhead in a single transaction.
For Air Methods, the logic runs deeper. Owning the billing layer gives the company direct visibility into transport volumes, payer mixes, and reimbursement trends across entire regional markets. That data is operationally valuable in ways that go far beyond processing claims. It tells Air Methods exactly where demand is growing, where reimbursement rates are favorable, and where competitor EMS agencies are financially vulnerable. The billing business functions as a market intelligence operation as much as a revenue stream.
The deals are typically structured as asset purchases rather than stock acquisitions, which keeps them below the disclosure thresholds that would attract federal antitrust attention. A billing company processing claims for a dozen rural EMS agencies might sell for well under $10 million – small enough to close without regulatory filings, but large enough to matter to the seller and strategically significant to Air Methods when multiplied across dozens of similar transactions in different states.
What Regional Billing Groups Are Actually Selling
The core asset in these deals is not software or office space. It is client relationships – specifically, long-term service contracts with municipal EMS agencies, fire departments with transport functions, and private ambulance operators. These contracts are often renewed on autopilot, running for years without competitive rebidding. A billing company with ten such contracts locked in over five-year terms is essentially selling a predictable, annuity-style revenue stream, and Air Methods is paying accordingly.
The secondary asset is staff knowledge. Ambulance billing requires a very specific understanding of transport codes, mileage documentation requirements, and the documentation standards that determine whether a claim pays at the base rate or gets denied entirely. Experienced billers in this space are not easy to recruit, and a regional shop with a stable team of eight to twelve coders represents years of accumulated institutional knowledge. Air Methods retains these teams post-acquisition, at least initially, which smooths the transition for the EMS clients who notice the change only when the payment remittance address shifts.
There is also a compliance angle that makes these acquisitions particularly attractive. The Office of Inspector General has historically scrutinized ambulance transport billing more aggressively than almost any other Medicare category. Claims for medically unnecessary transports, upcoded mileage, and inadequate documentation of patient condition are recurring enforcement targets. A large company with dedicated compliance counsel can absorb that regulatory risk more efficiently than a small regional shop operating with a part-time compliance consultant. Sellers often describe the OIG exposure as one of the less-discussed but very real factors pushing them toward an exit.
What changes most visibly for the EMS agencies being served is not the quality of billing work but the negotiating dynamic. A locally owned billing company was, in most cases, genuinely dependent on its EMS clients and responsive to their concerns. Air Methods, operating at scale with clients across multiple states, carries a different kind of leverage. Service level disputes, contract renegotiations, and pricing adjustments all play out differently when the vendor is a subsidiary of a national air medical company rather than a small business owner who grew up in the same county as the fire chief.
The EMS agencies most affected are those in rural and semi-rural markets – exactly the communities where Air Methods has historically concentrated its air transport operations. The overlap is not coincidental. Rural markets tend to have weaker municipal procurement processes, fewer vendor alternatives, and EMS leadership teams that are stretched thin managing day-to-day operations. When the billing company they have worked with for fifteen years is acquired, many rural agencies simply accept the transition rather than go through the disruption of a competitive RFP process. Air Methods is banking on that inertia.
Where This Leaves Independent Operators
Independent ambulance billing companies that have not yet received acquisition offers are increasingly aware that the market is moving around them. The consolidation mirrors patterns seen in other service verticals where a dominant operator used acquisitions of ancillary businesses to entrench its position – regional funeral home chains consolidating under SCI networks followed a similar trajectory, where the acquirer used scale advantages to make independent competition progressively harder. For ambulance billing shops still operating independently, the question is not whether consolidation is coming but whether they can reach sufficient scale to remain competitive as Air Methods continues buying.
Some regional operators are responding by forming loose consortiums – sharing compliance resources, investing jointly in billing software platforms, and presenting themselves to prospective EMS clients as a more stable alternative to a national corporation with divided loyalties across air and ground transport markets. Whether those arrangements hold together under continued acquisition pressure is an open question. Air Methods has demonstrated patience with its acquisition strategy, and the company does not need to buy every independent shop to achieve its objectives – it needs enough of them to control the data and the client relationships that matter most.
The billing companies that have already sold tend to describe the decision in practical terms: the price was right, the regulatory environment was getting harder, and the next generation of ownership was not in place. What they are slower to discuss is what happens to their former EMS agency clients in year three or four of the new arrangement, when Air Methods has fully integrated the acquisition and begins optimizing the contract terms on its own timeline.
Frequently Asked Questions
Why is Air Methods buying ambulance billing companies?
Air Methods gains control over EMS revenue cycles, payer data, and regional market intelligence – assets that support both its billing and air transport operations.
How do these acquisitions affect local EMS agencies?
EMS agencies often continue receiving billing services without disruption, but the negotiating dynamic shifts as they move from a local vendor to a national corporate operator.