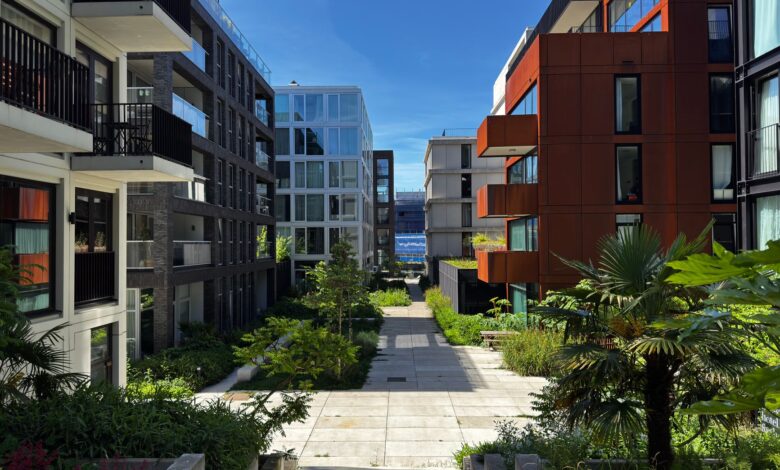
The Quiet Consolidation Happening in Your City’s Green Spaces
Landscape architecture has long been a cottage industry – regional firms with deep local roots, principal-led studios where the founder still walks job sites and knows every municipal planner by name. These are not flashy businesses. They design parks, campus master plans, waterfront revitalizations, and residential developments. They win awards at regional conferences. They are rarely written about in financial press. That invisibility is exactly what makes them attractive to private equity rollup platforms right now.
Over the past two to three years, a growing number of mid-sized landscape architecture and land planning firms have quietly sold majority stakes or full ownership to PE-backed platforms. The deals rarely generate press releases. The firm keeps its name. The founding principal often stays on for a transition period. And the PE platform moves on to acquire the next firm in the next market. The industry is being consolidated, city by city, without most clients noticing.
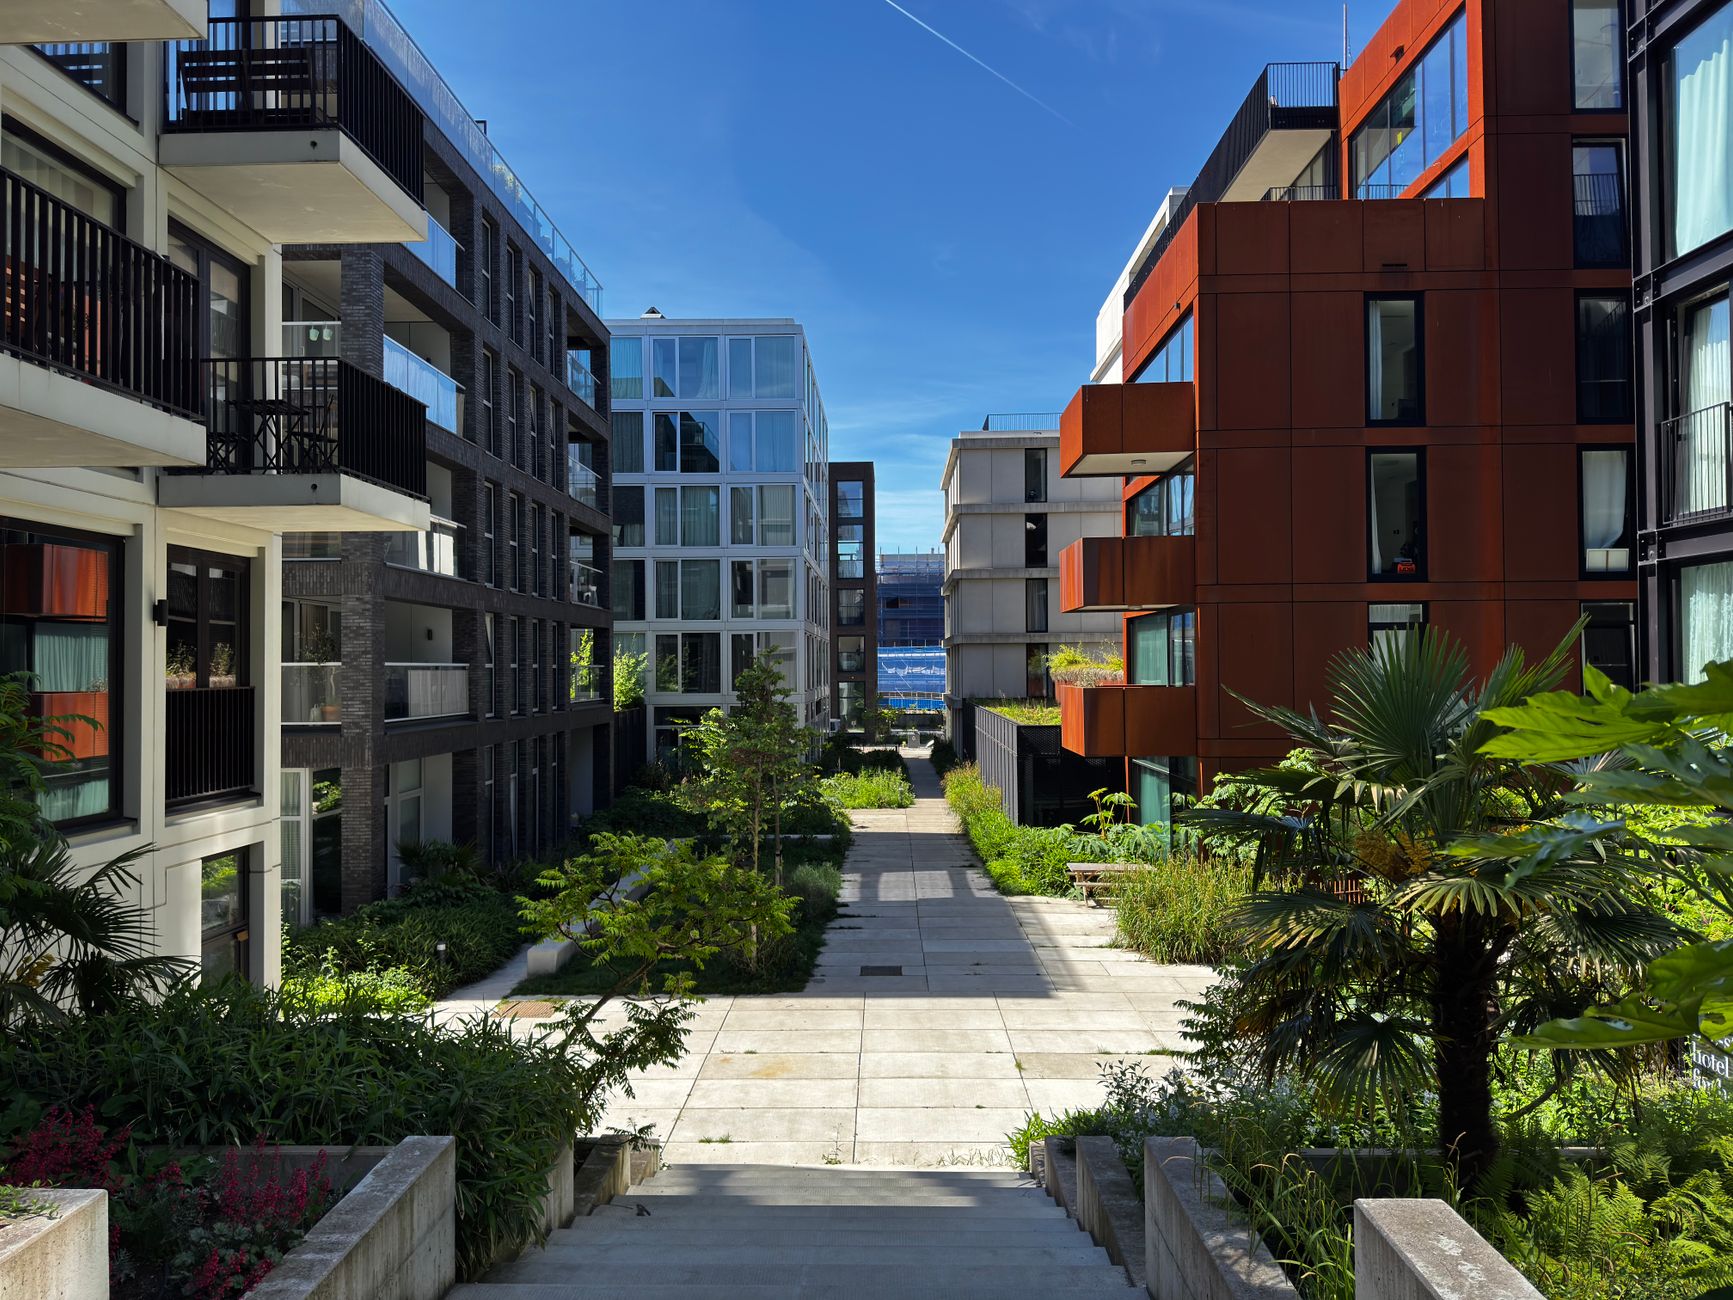
Why Landscape Architecture Fits the Rollup Model
Private equity rollups follow a specific logic: find a fragmented industry with recurring demand, acquire regional operators below the valuation multiples commanded by larger platforms, fold them into a centralized back office, and eventually sell the combined entity at a higher multiple than any single firm could achieve alone. Landscape architecture checks most of those boxes. The industry is populated by hundreds of firms in the 10-to-75-employee range, most of them founder-owned, many with no clear succession plan, and nearly all generating stable revenue from repeat public-sector and developer clients.
The recurring revenue angle matters particularly here. Municipal parks departments, state transportation agencies, university systems, and large residential developers all generate multi-year project pipelines. A landscape architecture firm with a strong public-sector client base effectively has a quasi-contracted revenue stream. That predictability is exactly what acquisition platforms use to justify financing from lenders. The revenue is not glamorous, but it is dependable in a way that purely project-based businesses are not.
Talent is the third factor. Landscape architecture has a genuine bottleneck at the licensed professional level. Registered Landscape Architects take years to credential, and the pipeline of new graduates is narrower than demand in many regions. When a PE platform acquires a firm, it is not just buying revenue – it is buying licensed capacity in a market where that capacity cannot be quickly replicated. That scarcity dynamic supports pricing power, and it gives the rollup platform a structural advantage over organic competitors trying to grow through hiring alone.
What Founders Are Actually Selling
Most founders entering these deals are in their 50s or early 60s, facing the classic professional services succession problem. They built a firm worth real money on paper, but converting that value to cash is genuinely difficult when your business runs on relationships and your name is on the door. A strategic sale to a PE rollup solves that problem. The founder receives a cash payment at close, typically retains a minority equity stake in the combined platform, and keeps a management role long enough to hand off client relationships without disrupting project continuity. It is a cleaner exit than most partnership buyout structures allow for.
The downside arrives later, and it arrives predictably. Once the transition period ends and the founder exits entirely, the firms often begin losing the relational glue that generated their revenue in the first place. Municipal clients who trusted a specific principal-led firm find themselves dealing with account managers reporting to a regional director two states away. The work does not necessarily get worse, but the relationship does. And in an industry where public sector procurement is heavily influenced by trust and track record, that relationship degradation eventually shows up in the win rate on new contracts.
The Platform Players and Their Geographic Logic
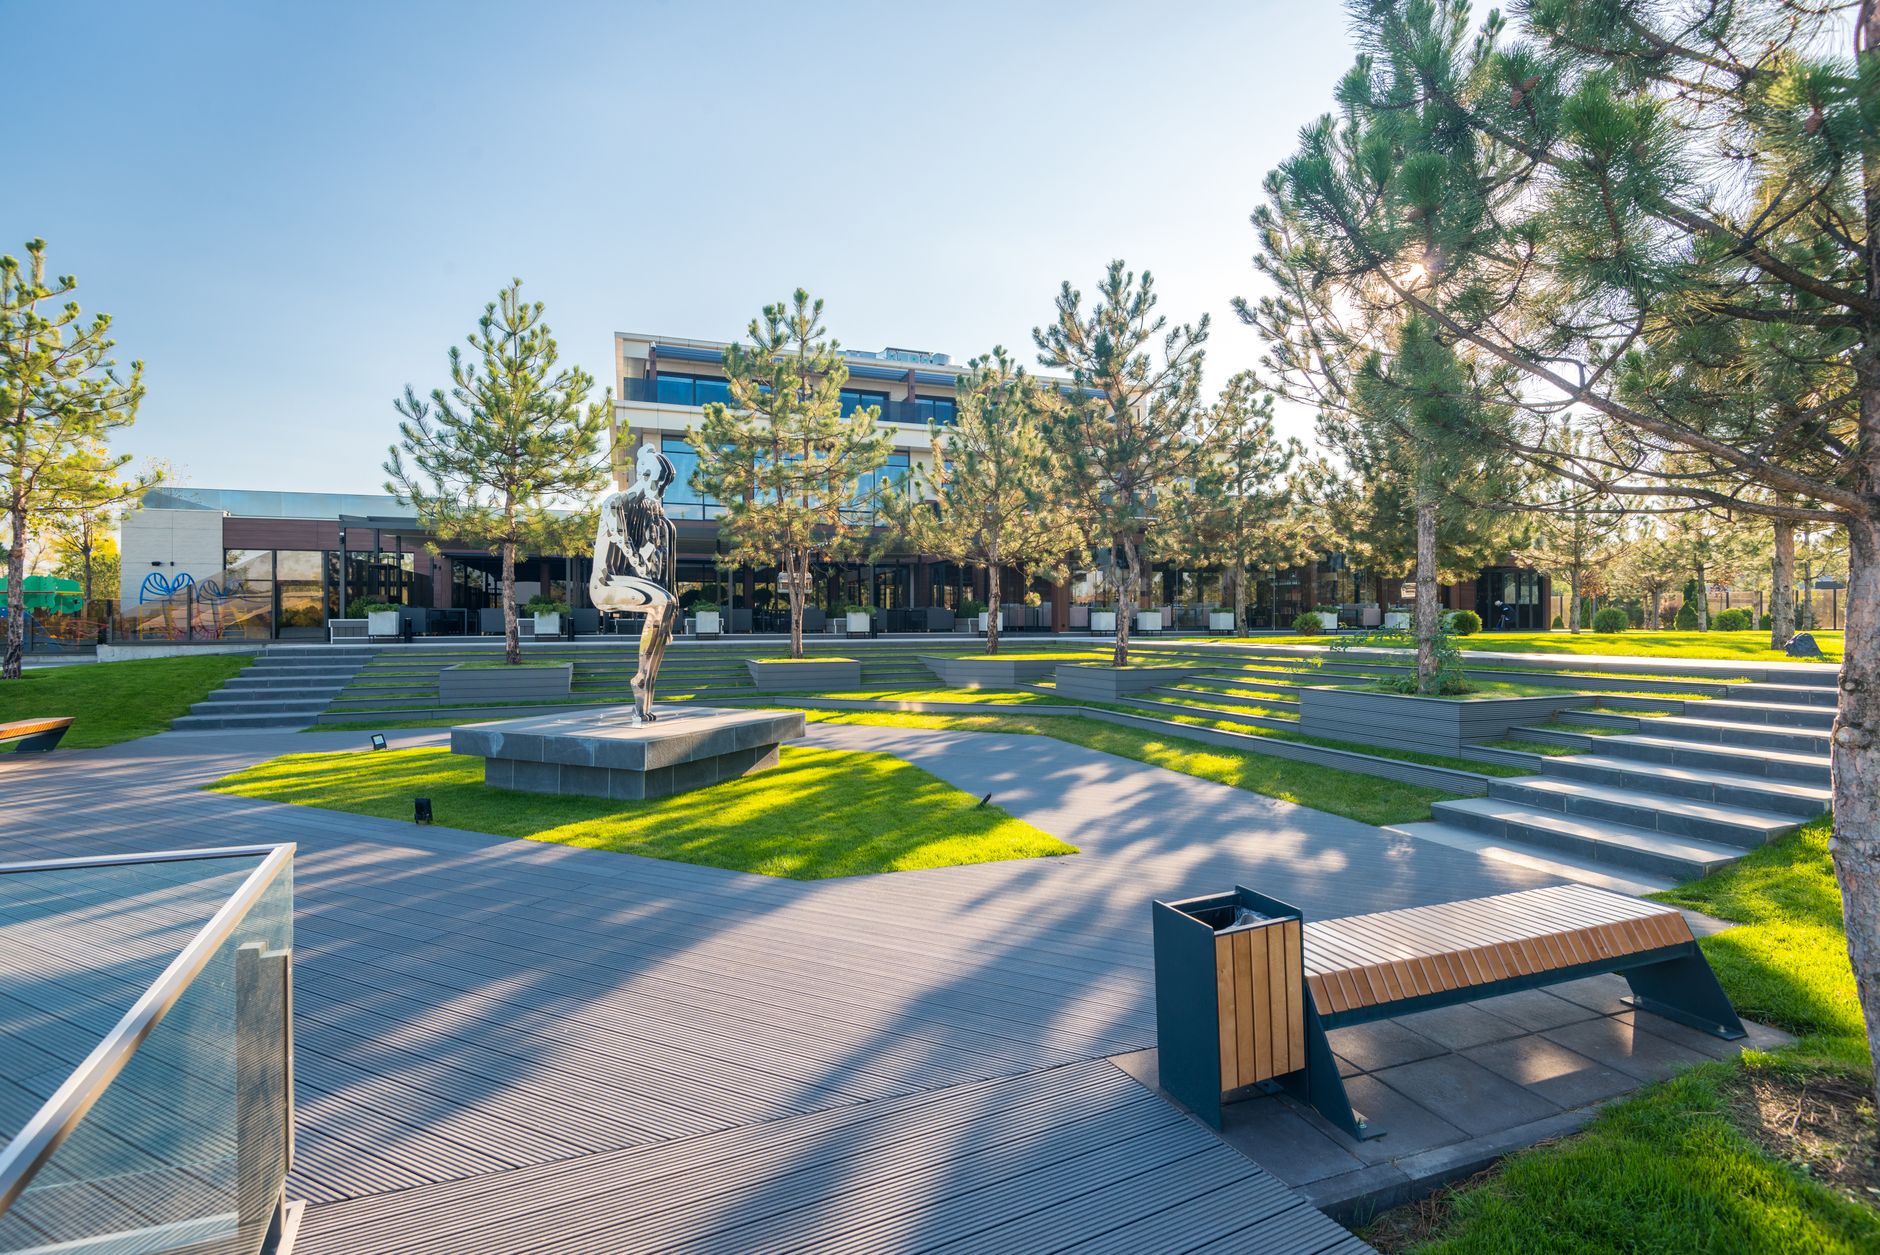
The rollup platforms operating in this space tend to organize their acquisition strategies around geography and specialization. Some focus on firms with heavy transportation and infrastructure experience – firms that do streetscapes, highway corridor design, and transit-oriented development. Others target residential planning heavy markets in the Sun Belt, where master-planned community development has driven consistent demand for large-scale land planning work. The geographic logic is deliberate: a platform wants contiguous market coverage, not random outposts.
This is the same playbook being run in other professional services trades. Regional roofing contractors have been absorbed through similar rollup structures, with acquirers using the same back-office centralization and multi-market coverage arguments to justify premium acquisition valuations. The sector changes, but the financial mechanics are nearly identical.
What makes landscape architecture somewhat different from other trade-service rollups is the regulatory layer. Landscape architecture practice is licensed at the state level, with reciprocity rules that vary significantly across state lines. A platform that acquires firms in eight states does not automatically have the ability to shift licensed staff across those markets. That creates friction that most rollup pro formas underestimate. The operational efficiencies that look clean in a spreadsheet run into licensing boards, continuing education requirements, and state-specific project type restrictions that slow the integration timeline considerably.
The centralized back-office savings – consolidated accounting, HR, procurement, insurance – are real and do materialize. But they typically arrive faster than the revenue synergies, which means the early months post-acquisition tend to look better on paper than they perform on the ground. Project management culture at principal-led firms is highly decentralized and instinct-driven. Imposing standardized project controls and utilization rate tracking on studios that never measured themselves that way creates internal friction. Some of the best technical staff – the ones with the most options – leave. That attrition rarely shows up in the acquisition model.
For clients, the practical question is whether the quality of design work actually changes. In the short term, continuity is usually maintained. In the medium term, it depends entirely on whether the platform is disciplined enough to keep the people who actually did the work. Rollup platforms that over-engineer their integration timelines tend to accelerate that talent departure. The ones that move slowly and leave studio culture largely intact hold value better – but they also take longer to generate the financial returns their own investors require. That tension does not resolve cleanly, and most platforms are still working out where they land on it.
Frequently Asked Questions
Why are landscape architecture firms attractive to private equity?
They generate stable recurring revenue from public-sector and developer clients, have a bottleneck in licensed professionals, and are mostly founder-owned with no succession plan.
What happens to firm quality after a PE acquisition?
Short-term continuity is usually maintained, but talent attrition and cultural friction often emerge during integration, which can affect client relationships over time.